Gold can be held directly or through financial products, but those forms do not create the same rights or risks. Understanding the instrument is more useful than starting with a universal portfolio percentage. Gold's price can rise or fall, and owning the metal does not itself generate interest or dividends.

Physical metal
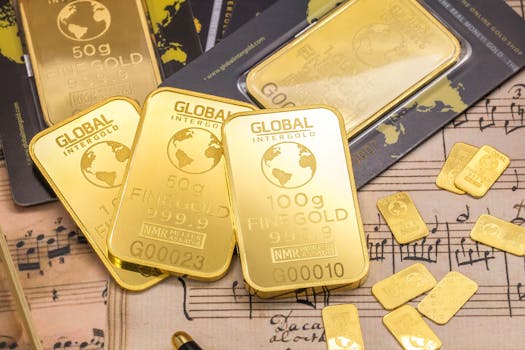
Bars and coins create questions about purity, authenticity, ownership, storage and insurance. Jewellery adds fabrication and retail charges that may not be recovered on resale. A quoted metal price is not the same as a dealer's purchase offer: premiums, spreads, testing and transaction costs affect the amount received.
Exchange-traded products
A product traded on an exchange can offer convenient exposure without arranging personal storage. Its prospectus still matters. Physical backing, derivatives, lending, custody arrangements and legal structure affect how exposure is delivered. Trading access does not guarantee that shares can be redeemed for metal by every investor, or that market prices will always match underlying value.
Mining shares and derivatives
A mining company is a business, not a bar of gold. Its shares reflect operational costs, financing, management, jurisdiction and production risks as well as metal prices. Dividends can change or cease. Futures and options add contract-specific features such as expiry, margin, leverage and settlement; they should not be treated as equivalent substitutes for unleveraged ownership.
Digital claims
A digital token described as gold-backed requires its own assessment of redemption rights, custody, audits, issuer obligations and transfer restrictions. A record on a blockchain does not independently prove that the promised metal exists or that a holder has an enforceable right to it.
Diversification has limits
Gold may behave differently from shares or bonds over some periods, but correlations change. Adding another asset does not automatically reduce overall risk, particularly if the position is large or purchased with borrowed funds. There is no allocation percentage that is suitable for every age, income level or investment horizon.
Tax treatment depends on the structure
Tax residence, account type, holding period and the legal form of the product all matter. Under U.S. federal rules, some individuals' long-term gains on physical gold are subject to a maximum collectibles rate of 28%, not a universal flat rate. Certain physically backed trusts can receive similar treatment; an ETF label does not guarantee a lower rate. These rules should not be transferred to other countries or taxpayer categories.
Questions before comparing products
A useful comparison records the asset actually owned, access to cash, total recurring and transaction costs, counterparty exposure and applicable tax rules. Neither past price gains nor an institution's purchase establishes suitability for another person. This is an explanation of ownership choices and their limits, not a recommended allocation or instruction to trade.
Editorial update — November 11, 2026: Revised to correct overgeneralizations and remove unsupported investment instructions and assurances. The original publication date is retained.
Leave a Reply