The Federal Reserve raised its policy rate by a quarter percentage point in September 2026, taking the target range to 3.75%–4.00%. During the same week, reports indicated that the central bank was considering higher asset thresholds for enhanced supervision of large banks.
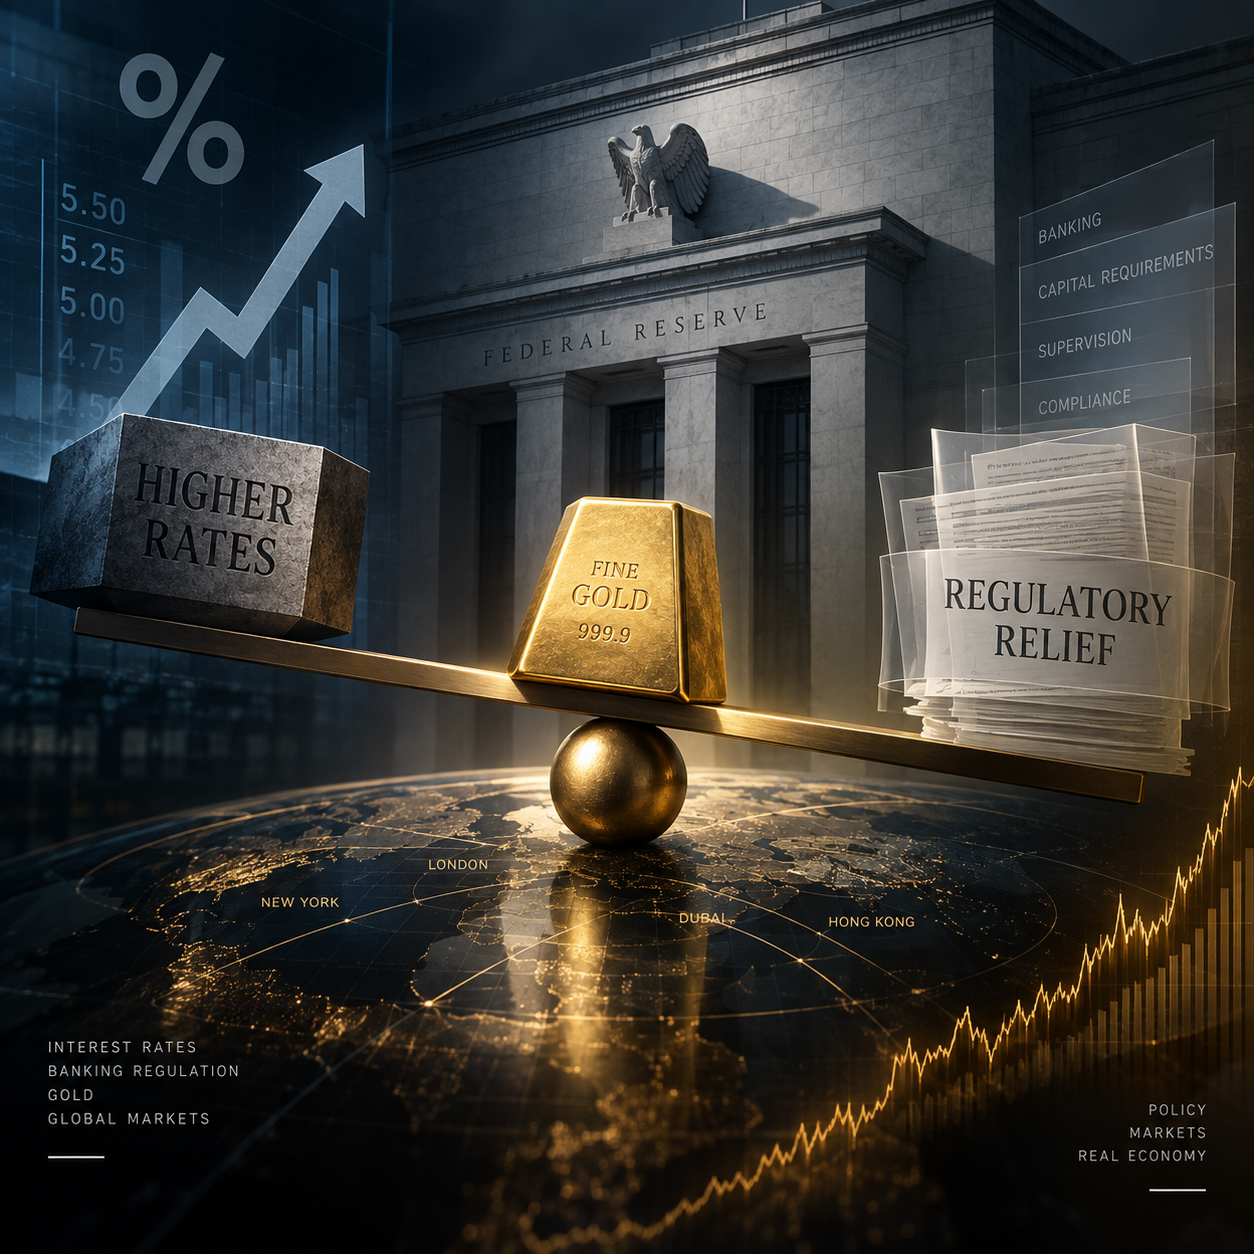
At first glance, the two moves appear contradictory: one arm is making money more expensive to restrain inflation, while another may loosen part of the regulatory framework around banks. The combination is better understood as a division between monetary tightening and supervisory reform.
For gold, that division creates two opposing forces. Higher rates and bond yields weigh on a non-yielding asset, while financial and political uncertainty strengthens its defensive role.
What did the Federal Reserve actually decide?
On September 16, the Fed unanimously raised interest rates by 25 basis points, its first increase since 2023. The statement said inflation remained elevated, even as economic activity, investment and employment remained relatively firm.
Officials’ projections placed the median federal funds rate at 4.1% at the end of 2026. From the current midpoint, that is consistent with another quarter-point increase before year-end.
It is not, however, a guaranteed decision. Recent comments from Fed officials indicate a willingness to tighten further if inflation is shown to be driven not only by energy, tariffs and supply disruptions, but also by resilient demand, services and investment. Markets are pricing a meaningful probability of another increase; the Fed has not pre-committed to one.
What is the bank-supervision proposal?
Separately, reporting based on people familiar with the discussions said the Fed may raise the asset threshold for its most intensive bank supervision from about $700 billion to roughly $960 billion. Another threshold attached to selected requirements could rise from $100 billion to $150 billion.
No final proposal has been issued. The figures should therefore be treated as a policy direction under consideration, not as a rule already in force.
Supporters can describe the change as technical indexation: old thresholds may no longer reflect the nominal growth of the economy and banking system. Critics see a practical reduction in the number of institutions exposed to the strictest scrutiny.
The real dispute is not the arithmetic alone. It is the point at which a reasonable regulatory update begins to weaken the ability to identify liquidity, interest-rate and concentration risks early.
Is a repeat of 2008 a fair comparison?
A direct comparison with the 2008 financial crisis goes beyond the available evidence. That collapse emerged from a broad system of subprime lending, complex securitisation, high leverage, weak underwriting and poorly regulated derivatives. Adjusting one supervisory threshold does not recreate that system by itself.
The closer precedent is the 2018 easing of oversight thresholds for midsized banks, followed five years later by the failures of Silicon Valley Bank and Signature Bank. Even here, causation should not be reduced to one legal change. Concentrated deposits, weak liquidity management, bond losses, rapid withdrawals and supervisory failures all contributed.
History therefore provides a warning worth examining, but not proof that another 2008-style crisis is approaching.
Why are higher rates and lighter oversight not a complete contradiction?
Monetary policy and banking supervision operate at different levels. Interest rates address inflation and demand across the economy. Prudential rules determine how much capital, liquidity and examination individual institutions require according to their size and complexity.
A central bank can believe that borrowing costs need to rise while also believing that parts of the regulatory framework have become outdated or too broad. The combination nevertheless deserves attention: funding becomes more expensive while some banks may receive greater regulatory room. If interest-rate and liquidity risks are poorly managed, pressures resembling the regional-bank stress of 2023 could reappear without repeating 2008 in the same form.
What does this mean for gold?
Higher rates remain a short-term headwind
Gold produces no recurring yield. When nominal and real bond yields rise, the opportunity cost of holding it increases. Continued expectations of another Fed hike, especially alongside a firm dollar, may therefore keep gold under pressure in the near term.
Gold has shown unusual resilience
Despite the rate increase and elevated yields, gold did not enter a disorderly decline. It fell during the week and then recovered part of its losses, remaining near $4,285 an ounce in the latest weekly reading.
This resilience suggests that the traditional rates framework is no longer the only force in the market. Central-bank purchases, Asian demand, geopolitical risk, fiscal concerns and declining confidence in parts of the monetary system continue to provide structural support.
Regulatory relief has a two-sided effect
In the near term, lighter bank rules may be received positively by equities and lenders, improving risk appetite and slightly reducing defensive demand for gold.
Over a longer horizon, the same policy could support gold if investors conclude that it increases the probability of future financial instability. The proposal is not an immediate bullish signal, but it adds another layer to the risks that can strengthen gold’s role outside the credit system.
The market reaction matters more than the headline
The most useful signal now is not another dramatic headline, but the way gold behaves relative to the dollar and Treasury yields.
If yields rise and gold remains firm, structural and defensive demand is absorbing monetary pressure. If higher yields combine with a stronger dollar and weaker physical demand, the correction could deepen. A decline in yields or renewed banking stress would push gold back toward the centre of the market debate.
Readers can follow the dated market record in Gold Price Analysis and the longer-term relationships in Gold Essentials.
Conclusion
The essential facts are sound: the Fed raised rates, officials’ projections allow for another increase, and genuine discussions are taking place about higher thresholds for enhanced bank supervision.
Claims that a repeat of 2008 is imminent are not supported by the evidence. The proposal is unfinished, and today’s banking system is not identical to the mortgage and derivatives structure that produced the global financial crisis.
The more accurate picture is an unusual policy mix: more expensive money and potentially lighter supervision for some banks. For gold, that is neither purely bullish nor purely bearish. Rates and yields remain a near-term obstacle, while financial, fiscal and geopolitical risks continue to protect its longer-term defensive demand.
Documentation references
- Federal Reserve interest-rate statement
- Federal Reserve economic projections
- Report on the proposed supervisory thresholds
- Market account of gold’s response to the rate increase
Disclaimer
This article is provided for documentation and general analysis only. It is not a recommendation to buy, sell or hold any financial asset.