An economic assessment of October 14, 2026, published on October 15, 2026.
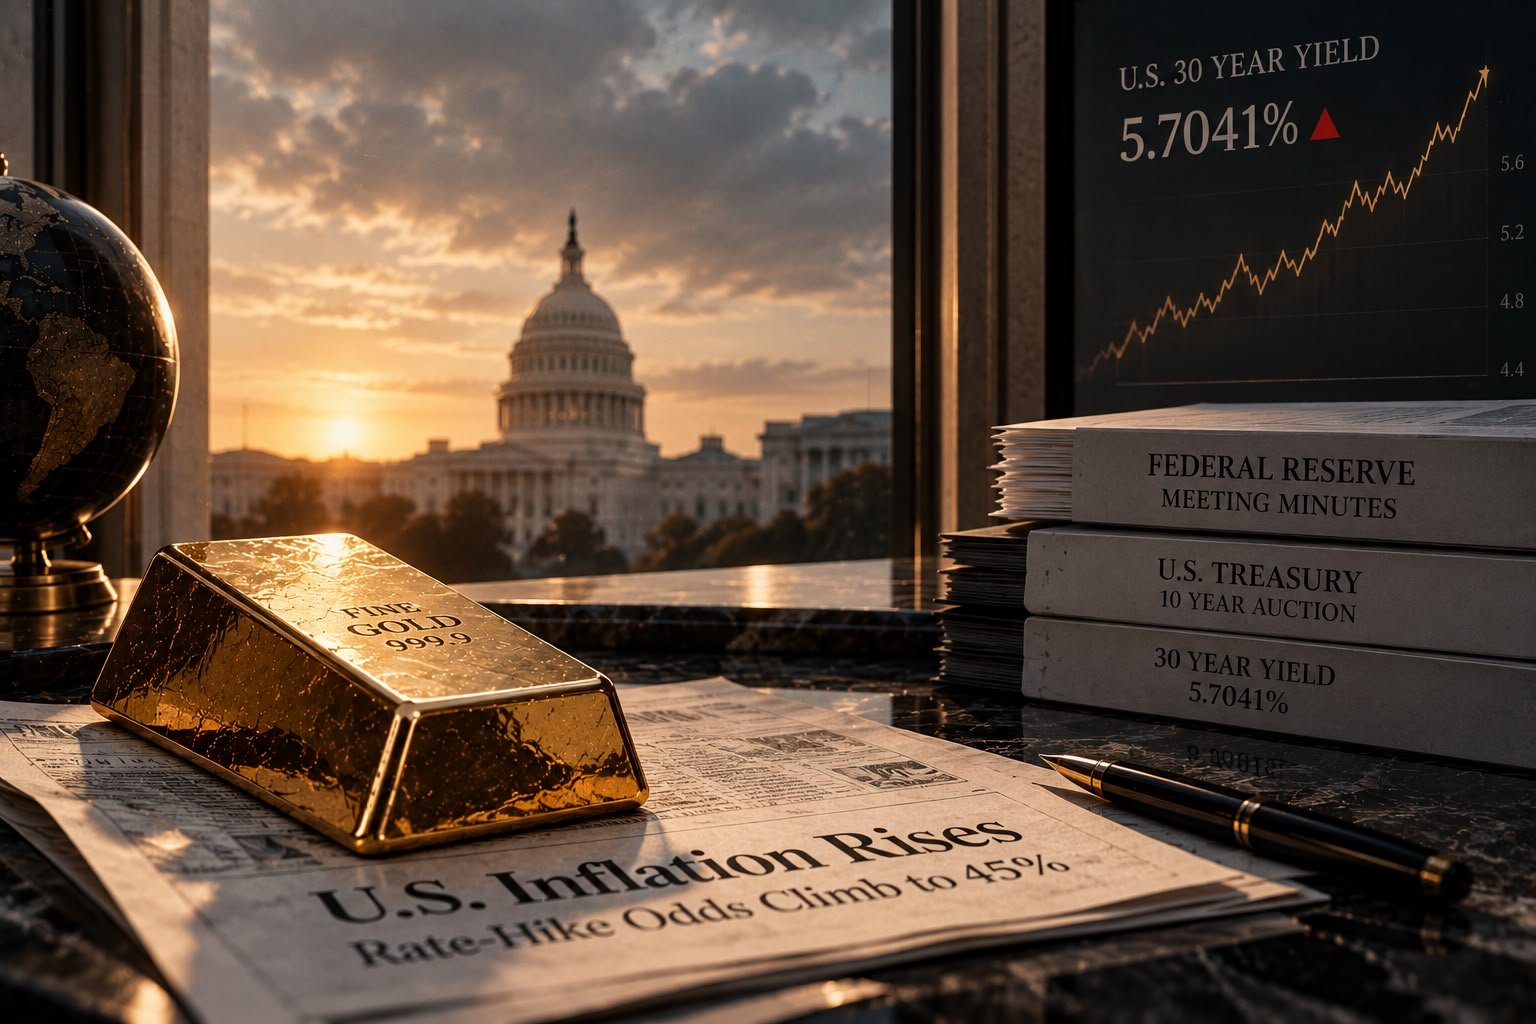
The surprise in the US inflation report released on Wednesday, October 14 was not simply that prices were still rising. It was the speed with which markets reopened the question of another Federal Reserve interest-rate increase. Less than two weeks after weak employment data had reduced expectations of further tightening, September consumer prices challenged the assumption that the Fed could comfortably wait.
Headline inflation reached 3.7% year on year, against expectations of 3.6% and August’s 3.4%. Prices rose 0.6% on the month, matching forecasts, while core prices, excluding food and energy, increased 0.3%, above the expected 0.2%. Annual core inflation rose to 2.6% from 2.4%.
One distinction matters: monthly core inflation did not accelerate from August. It was 0.3% in both months. The surprise was relative to the September forecast, rather than a faster monthly core reading. That distinction helps separate what the data actually showed from the expectations embedded in asset prices.
From weaker hiring to an inflation surprise
September payrolls increased by 29,000, unemployment stood at 4.2%, and average hourly earnings rose 0.1% on the month. Those figures provided a reason for caution: employment was losing momentum, and additional monetary restraint could carry a cost.
But slower hiring does not automatically eliminate inflation. Nor does it mean every component of demand is weakening together. Persistent price pressures across different parts of the economy can keep the case for tighter policy alive even when the employment figures argue for patience.
The Fed therefore faces competing risks. It must avoid applying more restraint than a softer labor market can absorb, while also avoiding a premature pause that allows price pressures to persist. This is a balancing problem, not an automatic response to a single release.
What a 45% rate-hike probability actually means
In an October 14 update published at 8:40 a.m. New York time, MarketWatch reported that LSEG-based pricing put the probability of an October increase at 45%, up from 20%. The same update recorded a 12-basis-point rise in the two-year Treasury yield and a seven-basis-point rise in the ten-year yield.
A move from 20% to 45% is an increase of 25 percentage points, not 25%. It also leaves a hike below an even chance. If the pricing framework contains only a hold and an increase, holding rates still accounts for roughly 55%. This was an immediate market snapshot, not a fixed probability for the remainder of October.
The Fed raised its target range to 3.75%–4.00% in September. Its next scheduled meeting is October 27–28. The inflation release reopened the timing question without settling the outcome.
What the Treasury response tells us
The two-year yield is particularly sensitive to expectations for near-term monetary policy. The ten-year yield also reflects longer-run growth and inflation expectations, the term premium, and the compensation investors require for holding duration. A larger rise in the two-year yield is consistent with a direct repricing of the near-term policy path, though it does not isolate every cause of the move.
This adds another layer to the relationship between bond-market stress and gold. Long-term yields can remain elevated even when the policy rate does not change. The CPI surprise adds the possibility of another near-term increase to that existing pressure.
Gold consequently faces two separate questions. Will the Fed raise rates? And will long-term yields decline if it does not? Answering the first does not answer the second.
Why this challenges gold
Gold pays no interest or recurring coupon. When competing assets offer more attractive returns, the opportunity cost of holding it can rise. But the more useful comparison involves expected real yields, rather than nominal yields alone.
If nominal yields rise because investors expect tighter monetary policy, and real yields rise with them, gold may become less attractive at the margin. If higher nominal yields primarily reflect higher inflation expectations, the implications can differ. A nominal-yield increase is not sufficient evidence that real yields have risen by the same amount.
The dollar provides another channel. A stronger US currency can make dollar-priced gold more expensive for buyers using other currencies. Yet neither the dollar nor Treasury yields establish the size of gold’s price response on their own. That requires a separate, timestamped observation of the metal.
The market outcome for October 14 is recorded in the session’s gold-price record. Spot prices must remain distinct from futures, and intraday observations from closing prices. A quotation recorded before the inflation release cannot establish the reaction afterward.
Energy: a temporary shock or a broader price problem?
Higher gasoline costs help explain the headline inflation acceleration. The monetary-policy question is whether those costs spread through transportation, production and services, and whether households and businesses begin changing their expectations, wage demands and pricing decisions.
A temporary, contained energy shock can call for a different response from persistent pressure extending across the economy. A core inflation surprise does not, by itself, prove that energy caused every increase outside the energy category. The components must be examined rather than assigned a single explanation.
For gold, energy disruption can work in opposite directions. It can encourage demand for protection against uncertainty and inflation. It can also increase the likelihood of tighter policy and higher yields. Which channel dominates depends on the market response and underlying demand, not simply on the geopolitical headline.
Falling real earnings complicate the decision
BLS reported that real average hourly earnings for all employees fell 0.5% in September and 0.7% over the year. The monthly decline combined a 0.1% increase in nominal hourly earnings with a 0.6% increase in consumer prices.
That represents a loss of average purchasing power. It does not imply that every household will reduce spending by the same percentage: savings, credit availability, wealth and income distribution also matter. Nevertheless, sustained price increases exceeding wage gains can make future consumption more fragile.
Further tightening could add pressure to employment and financing. Waiting while inflation persists could delay the return to price stability. The policy decision therefore cannot be reduced to CPI alone.
Five forces to track in gold
- Policy and yields: Follow meeting expectations alongside real yields and the term premium, keeping these measures distinct.
- The dollar: Assess whether currency strength persists beyond the initial response to a release.
- Inflation, growth and employment: Test the consistency of price, wage and demand signals instead of projecting one indicator onto the whole economy.
- Energy and geopolitical risk: Balance safe-haven demand against the inflation and policy effects of higher costs.
- Investment, official and physical demand: Fund flows, futures positioning, central-bank purchases and jewelry demand may reinforce or offset monetary pressure. CPI does not measure these flows, so attributing the session’s movement to them requires independent evidence.
What the next releases test
At the end of October 14, producer prices and retail sales scheduled for October 15 were the next tests of cost pressures and consumer demand. Because this assessment is being published on October 15, the subsequent session belongs in the October 15 market follow-up; those releases should not be presented here as events that have yet to happen.
The analytical framework remains useful. Strong producer-price inflation together with resilient demand can increase tightening risks. More moderate prices and weaker demand can support patience. Nominal retail sales, however, may rise because prices are higher: they must not be treated automatically as evidence of stronger real purchasing volumes.
A better environment for gold does not necessarily require an immediate rate cut. A sustained decline in real yields and the dollar could help if investment demand is strong enough to absorb selling. Conversely, gold may remain under pressure despite a policy hold if competing assets continue to offer attractive real returns.
Inflation reopened tightening without deciding it
The employment report pointed to weaker hiring. The price report showed that inflation pressure had not disappeared. Between those signals, investors reassessed monetary-policy risks. A market-implied probability reflects that reassessment; it is neither a Fed commitment nor a final verdict on gold.
Gold responds to more than the inflation number itself. It responds to the implications for policy, real yields and the dollar, and to the demand that meets those pressures. The question for the rest of October is how the Fed balances weakness in parts of the economy against persistent price increases, and how the bond market translates that balance into a return that competes with the metal.
Rate probabilities and yield changes refer to the market snapshot identified above. The scenarios are conditional economic analysis, not personalized buying or selling advice.
Sources and data notes
- BLS — September 2026 Consumer Price Index, released October 14.
- BLS — September 2026 Real Earnings.
- BLS — September employment report.
- Federal Reserve — September 16 policy decision and meeting calendar.
- MarketWatch / LSEG — October 14, 8:40 a.m. ET market snapshot.
- Reuters — expectations ahead of the CPI release.