A research review based on information available through November 19, 2026.
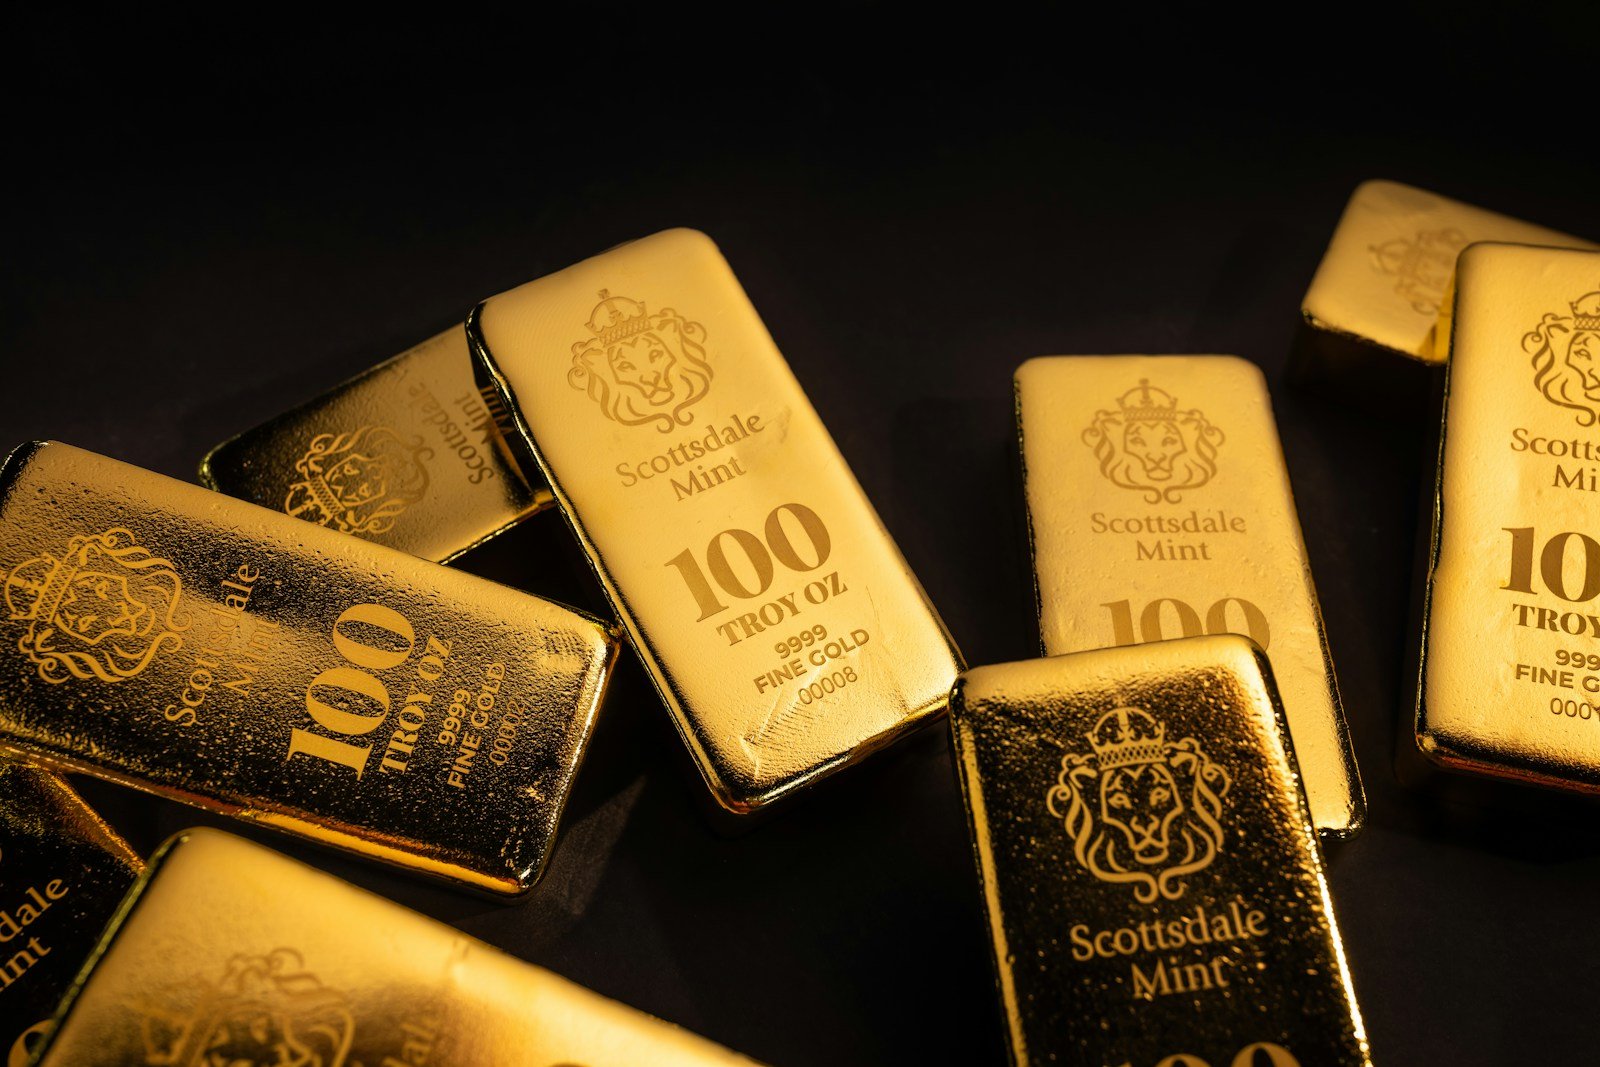
It was a week built for a gold rally that never came. The United States struck a missile facility on Iran’s Qeshm Island, attacks widened against American bases and Gulf oil tankers, and a textbook safe-haven bid should have followed. Instead gold slid to roughly $3,693 an ounce in Asian trade — its weakest since September 2025 — before settling near $3,721, according to trading data carried by FXStreet and Kitco. The question worth sitting with is not how far gold fell, but why the classic refuge shrugged off a live conflict and bent instead to the minutes of a meeting in Washington.
When the Fed Is the Story, Not the Map
The answer starts with a shift in the monetary regime itself. Minutes from the Federal Open Market Committee’s October 27–28 meeting, released on November 18, revealed a committee leaning plainly toward tightening rather than easing. The Fed left rates unchanged in October, but the minutes called the decision “a close call” and showed that nearly all participants expected to raise rates in December. Two officials went further, floating a possible half-point move if inflation stayed unfavorable, per Kitco’s reading of the record.
This is not an economy cutting rates and hunting for shelter. The producer price index was described as “uncomfortably high,” and October’s consumer inflation print ran hotter than forecast. Against that backdrop, Federal Reserve Governor Christopher Waller said he favors a December hike and is open to a half-point increase if core CPI comes in hot. CME’s FedWatch tool puts the odds of a quarter-point hike at the December 8–9 meeting near 92–95 percent. When the next move in rates is all but certain to be upward, gold stops being a coveted asset and becomes an expensive one.
Real Yields: The Cost Gold Cannot Pay
The relationship between gold and interest rates reduces to a single idea economists settled on decades ago: gold produces no income. No coupon, no dividend, no compounding. When the real yield — the nominal yield on bonds minus expected inflation — rises, so does the opportunity cost of holding a barren asset. Put plainly, every dollar parked in gold is a dollar denied the yield of a safe bond.
That is the real story behind the 2026 decline. The ten-year Treasury yield has climbed to about 5.07 percent and the two-year to roughly 4.80 percent, while the Fed works to tame inflation that refuses to settle. When a central bank lifts nominal rates faster than inflation expectations fall, the real yield rises, and a government bond paying 5 percent grows steadily more tempting than a metal that pays nothing. Gold is not falling because danger receded; it is falling because its safe alternative now pays more.
| Indicator | Reading (Nov 19, 2026) | What it means for gold |
|---|---|---|
| Spot gold | ≈ $3,721 (low of $3,693) | Weakest since September 2025 |
| Dollar index (DXY) | ≈ 103.65 (touched 103.96) | 19-month high — downward pressure |
| 10-year Treasury yield | ≈ 5.07% | Elevated opportunity cost |
| 2-year Treasury yield | ≈ 4.80% | Priced for continued tightening |
| December hike odds (FedWatch) | ≈ 92–95% for 25 bps | Near-certain upward rate path |
A Strong Dollar: The Other Side of the Same Coin
Gold is priced globally in dollars, so when the dollar strengthens the metal grows costlier for holders of other currencies and demand cools. The dollar index touched 103.96, a nineteen-month high, lifted by rising yields and by capital flowing into dollar assets during a moment of geopolitical strain. This strength is not separate from the rate story; it is an extension of it. High real yields pull capital toward the dollar, and a strong dollar weighs on gold. The two are not independent headwinds but two faces of one monetary system tilting toward restraint.
Why the Safe Haven Stayed Quiet
The escalation between Washington and Tehran was real and tangible, yet it produced no meaningful defensive bid for gold, as Kitco observed. The reason is structural, not situational. “Safe haven” is not an absolute property; it is always competing against opportunity cost. In a low or falling rate environment, fear wins, and gold climbs with every crisis. In a high and rising rate environment, cost wins, and the real yield swallows the risk premium before it ever reaches the price. An investor worried about war now has an alternative refuge that pays 5 percent — the Treasury itself — and has little need for a silent metal.
What History Says
None of this is new. The clearest precedent is the early 1980s, when the Fed drove rates to record highs to break the inflation of the 1970s. Real yields turned sharply positive, and gold collapsed from its 1980 peak near $850 to less than half that within a few years — even as geopolitical risk never disappeared. The pattern repeated in 2013 during the “taper tantrum,” when real yields jumped on expectations that the Fed would scale back asset purchases, and gold lost roughly a quarter of its value in a single year. The recurring lesson is that gold’s harshest stretches do not coincide with a calmer world; they coincide with rising real yields. What we are watching in November 2026 is the latest chapter of that same story, not an exception to it.
For the day-to-day picture, the gold price report for November 18 tracks the market move by move, while the gold price analysis section gathers the daily log, and gold essentials returns to the long-run forces behind these relationships.
Sources and Methodology
This review draws on the Federal Reserve’s official minutes and on coverage from reference financial institutions, without reproducing any outlet’s framing verbatim. Figures are attributed to their sources, and nothing here constitutes a recommendation to buy or sell.
- Federal Reserve — FOMC meeting minutes and calendar
- InvestmentNews — October minutes and the committee’s split over a hike
- FinanceFeeds — gold, dollar and yield data after the minutes
- CNBC — Governor Christopher Waller on a December hike
- CME FedWatch — December rate-decision probabilities
- Trading Economics — Federal Reserve policy rate path
Editorial note: This is an analytical research review intended for documentation and understanding, not investment advice. Figures are tied to the moment of publication and may change; events are attributed to their institutional sources.